Digital Transformation in Insurance: A Roadmap to Modernize Underwriting, Claims, and Core Systems
Key Takeaways
- Digital transformation in insurance means rebuilding how insurers sell, underwrite, service, and settle claims around data, automation, and connected platforms.
- It pays off: P&C insurers that invested more in analytics and AI ran combined ratios six points lower than slower adopters (WTW, 2026).
- Most insurers are mid-journey: only 23% have scaled AI enterprise-wide, and 71–79% still run legacy on-premises cores.
- Six trends lead in 2026: AI (including agentic AI), cloud and core modernization, APIs, low-code/no-code, IoT and telematics, and advanced analytics.
- The roadmap has five steps: assess maturity, prioritize by value, build the data foundation, partner for speed, and measure.
- Start narrow: Allianz cut simple-claim processing time by 80%, and our AI-powered OCR cut a US broker's underwriting time by 40%.
Introduction
Customers expect to get a quote, update a policy, and file a claim as easily as they order something online. Insurers still running those journeys on paper, email, and decades-old core systems are losing those customers to carriers that don't.
Most insurers know this. In Accenture’s Pulse of Change survey, 90% of insurance executives said they plan to invest more in AI in 2026. Yet KPMG’s 2026 survey found that no respondent had fully redesigned sales, distribution, or underwriting around AI. Spending is up. Reinvention is not.
Closing that gap requires deep engineering expertise in data and machine learning, which is why many carriers pair internal teams with partners for custom AI and ML development.
This guide explains what digital transformation in insurance means, its benefits, how it changes operations, the trends and technologies leading in 2026, how it differs across P&C, life, and health insurance, and a five-step roadmap, with real insurer examples and a client case study.
Map key systems, data, and high-ROI use cases into a modernization roadmap.
What Is Digital Transformation in Insurance?
Digital transformation in insurance redesigns an insurer’s products, processes, technology, and culture around data and automation. The goal is to price risk more accurately, serve customers across digital channels, and settle claims faster and at lower cost.
What Are the Core Building Blocks of Insurance Digital Transformation?
Insurance digital transformation rests on five building blocks: a data foundation, modern core platforms, AI and automation, digital channels, and people and governance.
- Data foundation: governed, integrated data that underwriting, claims, and customer teams can trust.
- Modern core platforms: policy, billing, and claims systems that are configurable and API-ready instead of rigid and batch-based.
- AI and automation: machine learning, generative AI, and workflow automation applied to underwriting, claims, and service.
- Digital channels: self-service portals, mobile apps, and agent tools that share one view of the customer.
- People and governance: training, clear ownership, and model governance that regulators can examine.
Why Is Digital Transformation Urgent for Insurers Now?
Digital transformation is gaining significance due to new regulations and advances in AI. In insurance, clients now compare their interactions with the product to consumer apps. As a result, expectations have risen for faster, easier, and smoother service. The expectations from the regulators are that documentation is provided to oversee automated decisions.
AI is now able to process documents, detect fraud, and create responses on a scale that seemed impossible a couple of years ago. Companies that put off adopting these technologies will have to bear the high costs of maintaining old systems, while competitors profit from modern ones.
What Are the Benefits of Digital Transformation in Insurance?
Digital transformation helps insurers improve underwriting accuracy, reduce operational costs, deliver better customer experiences, and respond faster to changing market demands.
By connecting data, automating workflows, and modernizing core systems, insurers can improve decision-making and build more efficient operations.
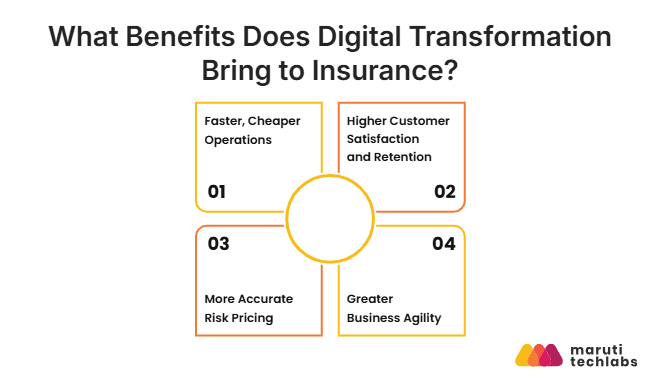
1. Faster, Cheaper Operations
Insurance workflow automation reduces manual data entry, document handling, and repetitive claims checks. Integrating automation with policy administration and claims systems also minimizes duplicate work and processing delays. Allianz reports an 80% reduction in processing and settlement time for simple claims handled by its agentic AI system.
2. Higher Customer Satisfaction and Retention
By using digital self-service platforms, online estimating tools, and real-time claims tracking systems, insurance companies have made their services easier than ever. Digital self-service apps allow clients to carry out existing processes without having to wait for an expert, while automated alerts inform them about the progress of their inquiries and renewals.
Faster responses and fewer service delays can improve customer satisfaction and support long-term retention.
3. More Accurate Risk Pricing
Telematics, IoT devices, and predictive analytics give insurers more detailed insights into individual and changing risk patterns. Auto insurers, for example, can use driving behavior to inform usage-based premiums, while property insurers can analyze sensor data to identify potential losses.
Better risk assessments help insurers price policies more precisely, refine underwriting decisions, and reduce exposure to avoidable losses.
4.Greater Business Agility
Cloud computing systems, modular models, and application programming interfaces facilitate product launches, integration of services from outside firms, and adjustments to the legislation without the necessity to replace the legacy software entirely.
Teams can more easily upgrade individual components and test them. This flexibility allows insurance companies to react more quickly to market fluctuations.
How Is Digital Transformation Changing Insurance Operations?
It transforms five parts of the insurance value chain: distribution, underwriting, policy servicing, claims, and risk and compliance. Each can be transformed on its own, so most insurers sequence them by ROI.
1. Distribution and onboarding: Digital quoting, e-signatures, and embedded purchase flows shorten the path from interest to policy. Omnichannel tools give agents, call centers, and apps the same customer record.
2. Underwriting and pricing: Models ingest more data, from telematics to third-party and unstructured documents, and score risk faster. Straightforward risks can be priced and bound automatically while complex ones go to underwriters. See how AI in underwriting works in practice.
3. Policy administration and service: Self-service lets customers change coverage, download documents, and renew without calling. Automated reminders and alerts replace manual outreach.
4. Claims: Intake, triage, coverage checks, fraud screening, and payout calculation are the most automated steps. Adjusters concentrate on complex or sensitive cases. Our guides to machine learning in insurance claims and AI agents for insurance claims cover the details.
5. Risk and compliance: Audit trails, model inventories, and monitoring turn compliance from a periodic exercise into a continuous one.
What Are the Key Insurance Technology Trends?
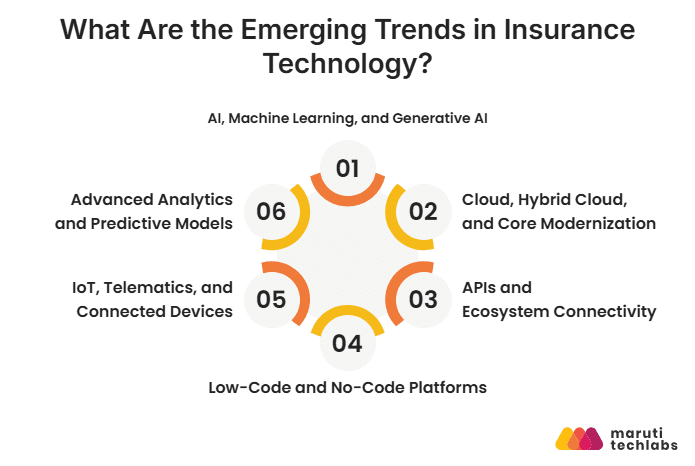
Six technologies drive most insurance digital transformation programs: AI, cloud and core modernization, APIs, low-code and no-code, IoT and telematics, and advanced analytics.
1. AI, Machine Learning, and Generative AI
AI in insurance is the use of machine learning, generative AI, and agentic AI for risk assessment, fraud detection, claims automation, document processing, and customer service.
Adoption is broad but shallow: Accenture found only 23% of surveyed insurers had adopted AI across the enterprise, so the opportunity is in scaling proven use cases. See our guide to AI use cases in insurance, or explore AI agent development services for multi-step claims and service workflows.
2. Cloud, Hybrid Cloud, and Core Modernization
Adopting cloud and hybrid cloud gives insurers scalable, secure infrastructure, real-time analytics, and a path off legacy cores. Majesco’s 2026 research found 71–79% of insurers still on legacy on-premise core solutions and only 24–30% using core cloud solutions. Hybrid approaches keep regulated data where compliance requires while new services run in the cloud.
3. APIs and Ecosystem Connectivity
APIs are standard interfaces that let an insurer’s systems exchange data with partners, payment providers, and distribution platforms. They are the plumbing behind embedded insurance, instant verification, and partnerships with fintechs and insurtechs.
4. Low-Code and No-Code Platforms
Platforms that are classified as low-code or no-code give business groups an opportunity to construct certain elements such as forms and workflow prototypes and thus work with few or no lines of code. These platforms support configurable tasks such as approval processes or specific forms. However, the performance of more complicated functionalities, e.g., logic that needs government regulation, requires coding and engineering.
5. IoT, Telematics, and Connected Devices
IoT and telematics devices can transmit risk data in real time. In this case, beyond pricing, these devices can help prevent risk by notifying clients if, for example, there is a leak or dangerous driving behavior.
6. Advanced Analytics and Predictive Models
Predictive models estimate claim likelihood, severity, churn, and fraud from historical and live data. They sit under most other trends, and their quality depends on data quality: in WTW’s survey, 42% of insurers reported data-related issues such as poor quality and limited accessibility as a significant barrier. Our data analytics consulting team helps insurers fix the foundation first.
How Does Digital Transformation Differ Across P&C, Life, and Health Insurance?
It differs mainly in what each line automates first: P&C focuses on claims and telematics, life on underwriting speed, and health on member service and compliance.
P&C Insurance
In property and casualty insurance, automated claims processing, telematics, and disaster response are common. This is due to the high occurrence of claims and the ability to collect various data. WTW reports that most companies already use predictive analytics for pricing and underwriting, and the next development is using AI in insurance claims.
Digital Transformation in Life Insurance
Digital transformation in life insurance centers on faster underwriting and a hassle-free purchasing process. According to a study by Munich Re carried out on 30 insurers, accelerated underwriting is said to be instrumental in taking us from a differentiating factor to a standard functional tool.
Studies on life insurance published by Equisoft show that 87% of insurance carriers use AI in at least one business process, and 38% of carriers say that the main challenge to achieving accelerated underwriting is the legacy systems that do not provide automation.
However, there are still challenges. According to McKinsey, most accelerated pathways apply only to fairly simple products such as term life and final-expenses policies, and the overall buying process is still very manual.
Health Insurance
Health insurance transformation centers on member self-service, claims and prior-authorization workflows, and wellness data. Heavy regulation and sensitive personal data make consent, security, and auditability the first design requirements.
How Do Insurers Manage Risk in Digital Transformation?
Insurers manage risk by pairing predictive analytics, IoT data, and AI with governance and security controls, because the same tools that reduce insurance risk create new ones.
- Predictive analytics estimate claim probability and let insurers adjust pricing and coverage as risk changes.
- IoT integration feeds streaming data from connected cars and smart homes into risk models, supporting prevention as well as pricing.
- AI governance keeps automated decisions explainable and fair. Under the National Association of Insurance Commissioners (NAIC) bulletin, insurers stay accountable for third-party model outputs, so keep an inventory of every underwriting, claims, pricing, and fraud model, test for unfair discrimination, and monitor performance after launch.
- Security and privacy need multi-factor authentication, encryption in transit and at rest, access controls, and clear consent for telematics and device data. Our data security services cover these controls.
What Challenges Do Insurers Face, and How Do They Overcome Them?
Five challenges recur: legacy systems, data quality, skills, compliance and security, and unclear ROI.
1. Legacy Systems
Old cores are costly to maintain and hard to integrate. Avoid a risky big-bang replacement. Wrap legacy systems in APIs, move high-value functions first, and retire old components gradually, following microservices best practices.
2. Data Quality and Access
Models trained on fragmented or poor data produce unreliable results. Invest in governance, a shared data model, and integration before scaling AI.
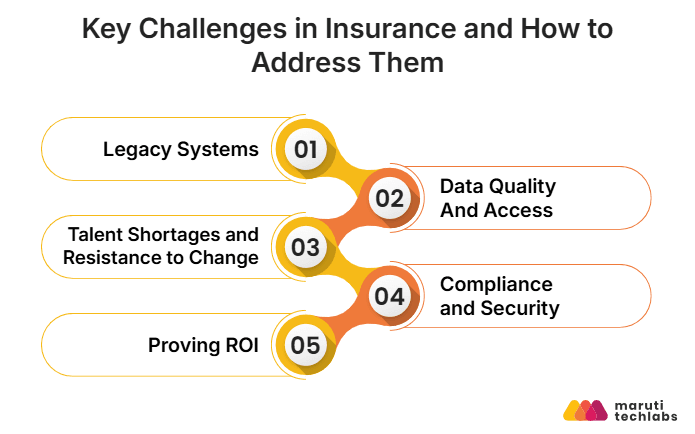
3. Talent Shortages and Resistance to Change
Accenture found that only 24% of insurance organizations had embedded continuous AI learning programs and just 5% were redesigning job roles for AI. Pair tools with training, involve underwriters and adjusters in design so they trust the outputs, and weigh upskilling against outsourcing.
4. Compliance and Security
Build governance, documentation, and monitoring from the start. It is far harder to add after launch.
5. Proving ROI
Define baseline metrics before launch, such as claim cycle time, cost per policy, and quote-to-bind rate, and track them. This is the gap KPMG’s survey highlights between activity and results.
How Do You Execute Digital Transformation in Insurance? (5-Step Roadmap)
Executing digital transformation in insurance involves assessing maturity, prioritizing use cases, building the right architecture and data foundation, selecting partners, and measuring results to guide continuous improvement.
Step 1: Assess Your Digital Maturity
Evaluate your data, technology, processes, and people to find strengths, skill gaps, and infrastructure limits. A structured assessment, such as a data maturity assessment, shows where you stand and keeps the roadmap realistic.
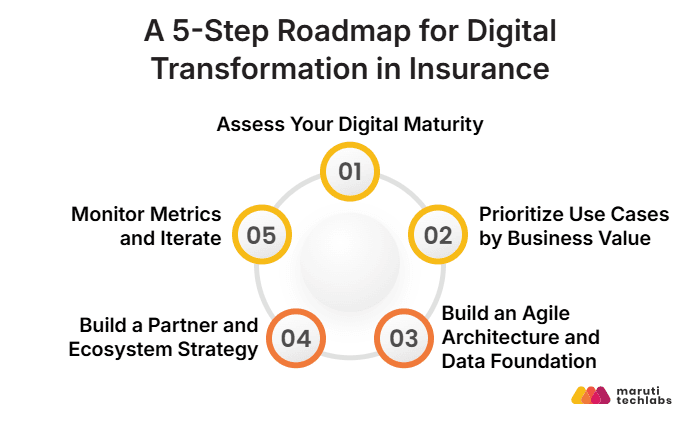
Step 2: Prioritize Use Cases by Business Value
Initiatives should be assessed according to profitability, efficiency, and customer impact. Start by driving high-volume, low-complexity processes with easily visible baselines to measure results. Prime candidates can be as simple as claims, inbound document processing, Self-service provision, etc.
Step 3: Build an Agile Architecture and Data Foundation
Deploy a flexible and cloud-based architecture with integrated APIs serving for prompt testing and scaling, along with connecting outdated ones. It is required to make improvements in data governance, integration, and interoperability so that every new case uses the reliable data already available.
Step 4: Build a Partner and Ecosystem Strategy
Cooperate with insurtechs, fintechs, and IT providers to accelerate movement, implementing embedded distribution and value-added services.
Step 5: Monitor Metrics and Iterate
Set KPIs for effectiveness, engagement, and finance, and regularly review and improve indicators based on customer feedback and real-time data.
What Should You Measure at Each Step?
Measure efficiency, engagement, and financial outcomes at every step, using KPIs like these:
Step | Example KPIs |
| Maturity assessment | Share of processes automated, data quality score, legacy system dependency |
| Use-case prioritization | Expected ROI, baseline cycle time, cost per transaction |
| Architecture and data | API coverage, time to launch a product change, data availability |
| Partnerships | Time to integrate a partner, share of premium from partner channels |
| Iteration | Claim cycle time, quote-to-bind rate, retention, combined ratio, employee adoption |
Conclusion
In the insurance sector, digital transformation has become necessary to stay competitive in price, speed, and service. While research shows positive results, most insurers cannot implement this technology across both their operations and their core activities.
Most likely, the most successful organizations will be insurers that pay close attention to organizing their data, selecting the right projects, and ensuring humans remain responsible for critical decisions.
Three trends will be important for the insurance industry in the years to come. One of them is the adoption of AI technology in underwriting and servicing, which will be enabled by APIs.
How Did Maruti Techlabs Automate Underwriting for a Leading US Insurance Broker?
We built a Python-based, AI-powered OCR pipeline that cut underwriting processing time by 40% for one of the largest insurance brokers in the United States. The project followed the same logic as the roadmap above: understand the workflow, prove the approach on a focused use case, then build and deploy.
What Problem Did the Client Have?
Underwriters verified customer documents by hand, which was slow, error-prone, and a source of customer drop-off. Four issues stood out:
- Highly manual document processing: underwriters reviewed documents, bank statements, credit scores, and other printed or handwritten records.
- Cross-verification by hand: driver’s licenses, vehicle registrations, and policy details had to be checked against original customer information.
- Rising volumes: growing application numbers made it hard to process quickly without adding manual workload.
- Error risk: missing information and inconsistencies could affect underwriting decisions and cost the client customers.
How Did We Automate It?
We validated the approach with a time-constrained proof of concept, then built and deployed an OCR pipeline in six phases:
- Understand the workflow: worked with the client’s team to find where AI could remove manual effort.
- Validate through a proof of concept: built confidence before committing to full development.
- Define the scope: set the project scope and timeline once the approach was proven.
- Build the OCR pipeline: developed a three-stage process covering image preprocessing, text detection, and character recognition.
- Verify extracted information: cross-referenced extracted data with registered customer credentials and flagged inconsistencies or missing information for manual review.
- Test and deploy: tested against client-provided data and multiple use cases before deploying to the client’s online platforms.
What Results Did the Automation Deliver?
Underwriting became faster, more accurate, and available around the clock:
- 40% lower processing time: automated underwriting tasks cut processing time by 40%.
- 24x7 document processing: the solution handles applications in parallel without continuous human intervention.
- Improved data accuracy: document classification and automated verification reduced errors and the risk of duplicate data.
- Stronger risk management: risk scoring and fraud insights strengthened underwriting security.
Talk to our AI and insurance engineering team about the right first use case for your business.
Frequently Asked Questions
1. How long does digital transformation in insurance take?
A focused use case can reach production in a few months, while a full core and data transformation often runs several years. Allianz built Project Nemo in under 100 days, and the underwriting automation above began with a time-constrained proof of concept. Plan in waves: deliver one measurable win, then reuse the data and architecture for the next.
2. Should an insurer build, buy, or partner for new capabilities?
Buy or configure commodity capabilities such as policy administration, billing, and standard portals. Build where your data or process is a competitive edge, such as pricing models or claims triage. Partner when you need speed or skills you lack, such as custom AI and ML development. In every case, the insurer stays accountable to regulators.
3. How can a small insurer or MGA start without a large budget?
Start with a document-intensive/repeated activity that requires a limited timeframe for validation. A focused pilot with a solid basis for the start, such as the OCR system, provides proof that makes it easier to proceed with a more extensive program.
4. How do you protect customer data when using generative AI?
Make sure that any personal data is excluded from public AI applications and make use of corporate solutions that are based on data processing agreements. Redact and tokenize the identifiers, limit access, log inputs/outputs, and make sure that it is a human who makes any decisions that affect customers. Our data security services help put these controls in place.
5. How do you process handwritten or unstructured claims and underwriting documents?
Use an OCR pipeline that preprocesses images, detects text regions, and recognizes characters, then validates the extracted fields against trusted records. Documents that fail validation go to a person. See how this works for claims in our guide to machine learning in insurance claims.
6. How do you choose a technology partner for insurance modernization?
Seek experience in the insurance field, production implementations with tracked results, and a structured approach that begins with trial projects. Clarify strategies for security and compliance in the project. Ask for examples of project implementations with metrics and confirm who will own the application and data at the end.